Another proposed acquisition of a U.S. business by a Chinese buyer just bit the dust, courtesy of CFIUS. Ant Financial and MoneyGram announced last week that they’ve called off their merger after CFIUS refused to sign-off on their efforts to address concerns about safeguarding personal data of U.S. citizens.
Ant Financial is controlled by Chinese billionaire and Alibaba founder Jack Ma, and according to this Shearman & Sterling memo, the deal’s demise reflects both rising concerns with national security issues involving acquisitions by Chinese buyers, & an increased focus on privacy issues. Here’s an excerpt:
The focus on China, especially on investments in the semiconductor and related industries, is well established. The Obama Administration blocked the acquisition of the U.S. subsidiaries of German semiconductor-equipment supplier AIXTRON SE by Chinese investors in 2016, and had a general policy of closely scrutinizing Chinese acquisitions in this sector. More recently, the Trump Administration stopped the acquisition of Lattice Semiconductor Corporation, an Oregon-based company, by a Chinese investor in September 2017, and senior officials have expressed concern about whether current U.S. laws on foreign investment are adequate to protect U.S. national security.
At the same time, CFIUS has over the past several years increased its focus on acquisitions of U.S. companies that have access to the personal information of U.S. citizens. The MoneyGram deal would have given Ant Financial access to the financial transactions of a considerable number of Americans. Concerns have been raised both within the Trump Administration and in Congress about whether such information would be adequately protected by foreign companies or used by foreign governments for geopolitical advantage.
The environment for Chinese deals in sensitive industries appears to be so tough that perhaps it’s not off base to paraphrase the last scene in the classic 1974 film “Chinatown” when it comes to summing up their chances of CFIUS approval – “Forget it, Jake – it’s a Chinese buyer.”
– Utilizing Social Media in Proxy Contests
– Planning for M&A Cybersecurity Risks
– True-Ups After Chicago Bridge: The Two Sides to Working Capital Adjustments
– Valuation Analysis: Key to Avoiding Failed M&A Deals
Remember that – as a “thank you” to those that subscribe to both DealLawyers.com & our Deal Lawyers print newsletter – we are making all issues of the Deal Lawyers print newsletter available online. There is a big blue tab called “Back Issues” near the top of DealLawyers.com – 2nd from the end of the row of tabs. This tab leads to all of our issues, including the most recent one.
And a bonus is that even if only one person in your firm is a subscriber to the Deal Lawyers print newsletter, anyone who has access to DealLawyers.com will be able to gain access to the Deal Lawyers print newsletter. For example, if your firm has a firmwide license to DealLawyers.com – and only one person subscribes to the print newsletter – everybody in your firm will be able to access the online issues of the print newsletter. That is real value. Here are FAQs about the Deal Lawyers print newsletter including how to access the issues online.
Mauri Osheroff – who until recently was Corp Fin’s Associate Director who oversaw the Office of Mergers & Acquisitions – was reading the transcript of our recent webcast with the Chiefs of OM&A from the past three decades. Mauri noted that the original office was called “Tender Offers & Small Issues” – they processed tender offers and Reg A offerings. Go figure. We don’t know when Reg A offerings dropped out of the picture.
The Office Chief back then was the legendary Ruth Appleton. Here’s Ruth’s obit, which details her SEC career and the obstacles she faced as a professional woman back then…
This Orrick blog notes that the FTC recently issued new guidance concerning the filing requirements under Item 3(b) of the HSR Form – which requires parties to file copies of all agreements relating to the transaction. Apparently, the FTC has found that some parties had been withholding relevant side agreements on the theory that they were ancillary to the main agreement or protected by privilege.
The blog says that the FTC doesn’t see things that way:
On December 20, 2017, the FTC issued additional guidance in connection with Item 3(b) of the HSR Form, which requests “copies of all documents that constitute the agreement(s) among the acquiring person(s) and the person(s) whose assets, voting securities or non-corporate interests are to be acquired.” The FTC’s post clarifies that “all” really does mean all:
[A]ny agreement entered by the parties or their representatives that bears on the terms of the transaction and is binding on the parties must be submitted as part of the HSR filing. This includes any agreement that alters the terms of the merger during the antitrust review process, regardless of where those commitments are written down. If there is an enforceable agreement that binds the parties to take actions related to antitrust clearance, it must be submitted as part of the HSR form. (Emphasis in original).
Nonbinding analyses & recommendations don’t have to be provided in response to Item 3(b) – although they may be responsive to other parts of the HSR Form. However, the agreements themselves must be provided – and the FTC says you can forget about work product or any other privilege claims.
This recent article from TheStreet.com summarizes a panel discussion among M&A experts about the state of shareholder activism. The panelists’ bottom line conclusion – in today’s environment, nobody’s immune from activism. Here’s an excerpt:
Insurgent investors have begun targeting better performing, and larger capitalization corporations in new sectors all of which suggests that no publicly-traded company can comfortably say it won’t find itself in an activist’s crosshairs, a panel of M&A experts said Thursday at The Deal Economy Conference.
“Nobody is immune to it,” said Adel Aslani-Far, a partner at Latham & Watkins LLP at the 15th annual The Deal Economy Conference in New York. “It no longer is that you have to be performing poorly to be the target of activism, you’ve seen in the last eighteen months to two years companies getting into activist sights that you would never have thought would get into activist sites, including companies with market caps that you would never have thought would have attracted the kind of investment by activism.”
The article notes that according to FactSet, there had been roughly 803 activist campaigns through November 2017, up from 737 for all of 2016. These included recent campaigns against high-profile targets such as Procter & Gamble and ADP. Activists are less inclined to break furniture in their approach to target companies, & are becoming more “elevated and mature” in their approach. In turn, this has prompted boards to become more sophisticated in their responses to activists, and perhaps more strategic in their overall thinking.
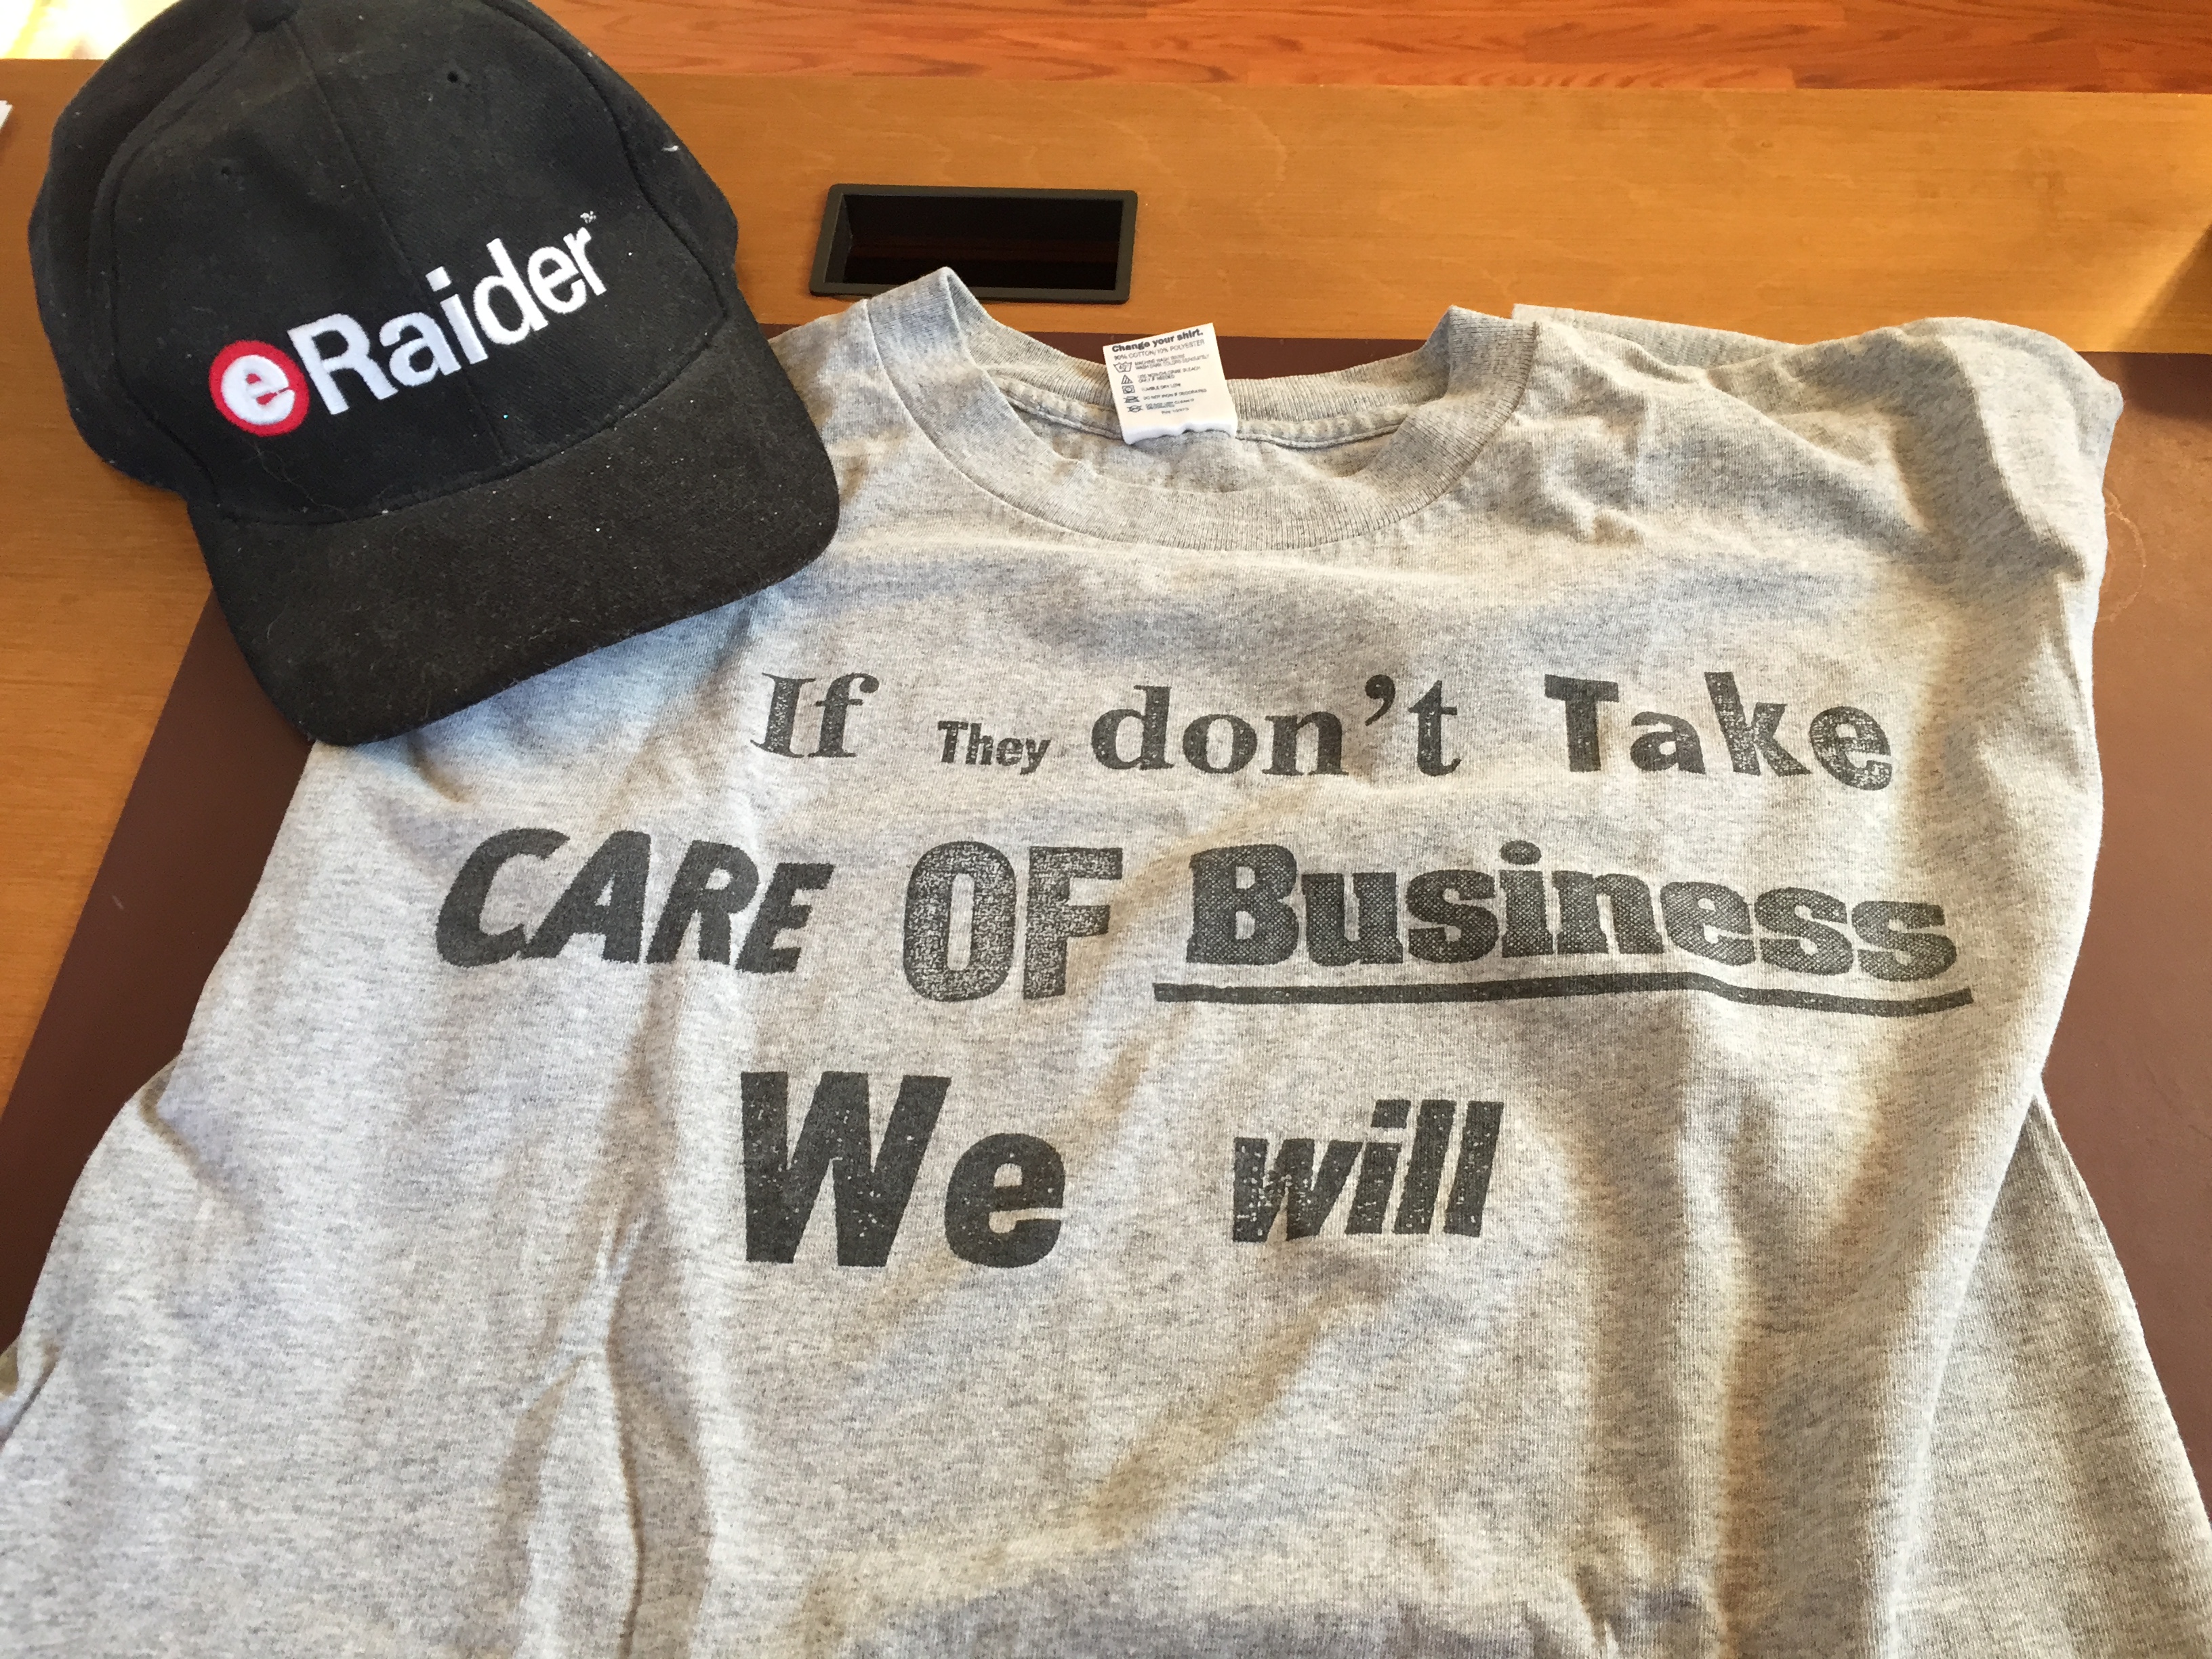
Recently, I blogged a “vote counting” story that involved eRaider, a widely-media covered fund during the Internet boom in ’90s that hoped to cash in on “message board” activism. eRaider’s business model was to buy 5% stake in small companies with good products, then get shareholders together to push for governance changes that would improve the company. The idea got a lot of publicity – but little “real life” traction and eRaider shut down in 2004.
Anyway, Lois Yurow sent in this pic of her vintage swag!
Here’s the latest edition of Houlihan Lokey’s annual termination fee study. The study reviewed 183 transactions involving U.S. company targets and involving at least $50 million in transaction value announced during 2016.
The study focused on termination fees both as a percentage of “transaction value” and “enterprise value.” Transaction value is the total value of consideration paid by an acquirer, and is generally equivalent to “equity value.” Enterprise value is the number of outstanding shares multiplied by the per-share offer price, plus the cost to acquire convertible securities, debt, and preferred equity, less cash and marketable securities.
Some of the highlights include:
– Termination fees as a percentage of transaction value during 2016 ranged from 0.8% to 5.1%, with a mean of 3.2% and median of 3.3%. The mean & median fees were identical with those reported in 2015, and nearly the same as reported in 2014 (3.2% mean & 3.3% median).
– Termination fees as a percentage of enterprise value were almost as steady. In 2016, the mean was 3.1% of enterprise value while the median was 3.2%. The mean & median fees were both 3.2% of enterprise value in 2015.
– Reverse termination fees as a percentage of transaction value varied depending on whether the deal involved a strategic or a financial buyer. In 2016, the median fee for strategic buyers was 3.6% for strategic buyers and 5.8% for financial buyers. The median fees for 2015 were 4.0% for strategic buyers and 6.1% for financial buyers.
– Median reverse termination fees as a percentage of enterprise value in 2016 were 2.9% for strategic buyers and 4.5% for financial buyers. In 2015, the median fee for strategic buyers was 3.7% and the median fee for strategic buyers was 6.5%.
Nixon Peabody recently posted its 2017 MAC Survey. Here’s an excerpt:
Of the 203 agreements surveyed, 181 (89%) contained a material adverse change in the “business, operations, financial conditions of the Company” as a definitional element. This is a slight decrease from last year’s survey, when this element appeared in 92% of all agreements. Meanwhile, just 15 of the acquisition agreements reviewed this year lacked a MAC closing condition, representing approximately 7% of all agreements reviewed, compared to 3% reported in the 2016 survey and 5% reported in the 2015 survey. We note that each of the deals valued at $1 billion or more in this year’s survey contained a MAC condition.
While last year’s survey suggested that recent pro-bidder trends could be leveling off, the small shift in this year’s results may tell a different story. More agreements contained the pro-bidder “would reasonably be expected to” language in the MAC definition – it appeared in 62% of the deals reviewed this year, while appearing in 54% of all deals reviewed last year. This language appeared in 61% of all deals reviewed in 2015, 56% of deals reviewed in 2014, 53% in 2013, 42% in 2012, 29% in 2011 and 13% in 2010. By defining a material adverse effect to involve circumstances that “would reasonably be expected to” lead to a MAC, a bidder introduces a forward-looking feature to the definition, allowing it to adopt a more lenient approach during negotiations over whether a material adverse change in the target’s prospects needs to be covered by the definition.
However, we also saw a slight decline in the usage of pro-bidder “disproportionately affect” language in the MAC exceptions during this year’s surveyed period. Such language appeared in 76% of the deals reviewed this year, while appearing in 81% of deals reviewed last year and 83% and 88% of deals reviewed the two years before—which evidenced a significant increase over the 73% found in our 2011 and 2012 surveys and the 48% and 40% found in our 2009 and 2010 surveys, respectively. “Disproportionately affect” language carves out exceptions from the MAC clause to ensure that bidders have the protections of the MAC clause in the event the target company suffers more greatly than its peers from a specified event, such as a general economic or industry downturn.
In any deal requiring regulatory approval, the time required to complete the regulatory process is a bit of a wild card – but that doesn’t mean you won’t get sued over it if there’s an unanticipated delay.
Fortunately, this Wachtell memo reports that a federal court wasn’t buying the claims in a recent lawsuit that statements about the anticipated timing of regulatory approval of a pending merger between M&T Bank and Hudson City Bancorp were misleading. Here’s an excerpt summarizing the plaintiffs’ claims and the court’s decision:
They alleged that statements of opinion about, among other things, the timing of the merger (“we currently believe we should be able to obtain all required regulatory approvals in a timely manner”) were misleading because, in light of regulatory issues that surfaced, the merger was likely to be delayed. The district court dismissed that claim as well.
In its decision last week, the court held those statements to be opinions, and that, as such, they were subject to the high bar set by the Supreme Court’s recent Omnicare decision. The district court stressed the importance of context—thecautionary language in the proxy. The allegedly misleading language, the court held,was “cherry-picked” out of surrounding warnings that M&T and Hudson City could not be certain if or when regulatory approvals would occur—that, indeed,there was “no assurance as to when or if the merger will occur.” Those warnings, and other failures of pleading, compelled the dismissal of the complaint.
The memo says that the court’s decision in this and an earlier proceeding are “an emphatic reminder” of the need for appropriate cautionary language in a merger proxy statement.
In this unanimous en banc decision, the Supreme Court of Delaware held that the Court of Chancery erred in giving no weight to Dell’s pre-deal stock price or the deal price when determining the fair value in this appraisal proceeding. In the Court’s view, “the market-based indicators of value – both Dell’s stock price and deal price – have substantial probative value” and “deserved heavy, if not dispositive, weight.”
Thus, once again giving a nod to the deal price, the Court cautioned the Court of Chancery to “be chary about imposing the hazards that always come when a law-trained judge is forced” to rely on discounted cash flow (DCF) analyses and “divergent partisan expert testimony.”
The Supreme Court observed that Dell’s sale process had many mechanisms designed to “ensure stockholders obtain the highest possible value.” It further concluded that “the trial court’s decision to give no weight to any market-based measure of fair value runs counter to its own factual findings.”
The Supreme Court’s emphasis on the significance of a deal price obtained through a sound process in determining “fair value” echoes the rationale underlying its decision earlier this year in DFC Global, and is consistent with a broader trend in Delaware appraisal cases toward increased deference to the deal price under these circumstances.